
Alphabet just reported its biggest quarter ever, and the stock fell off a cliff anyway. Alphabet Q3 2026 revenue hit $127.6 billion, up 25%, Google Cloud more than doubled, and shares still dropped about 8% after hours. The reason sits in two numbers: an $8.7 billion paper loss and a $51.4 billion spending spree that pushed free cash flow to negative $9.1 billion.
The results landed after the U.S. market close on Wednesday, October 28, 2026, in Alphabet’s official Q3 2026 earnings release, filed with the SEC as Exhibit 99.1 to Form 8-K. This was the company’s 13th straight quarter of double-digit growth, and the market punished it anyway: investors care right now about what the AI buildout costs, not growth.
The headline numbers
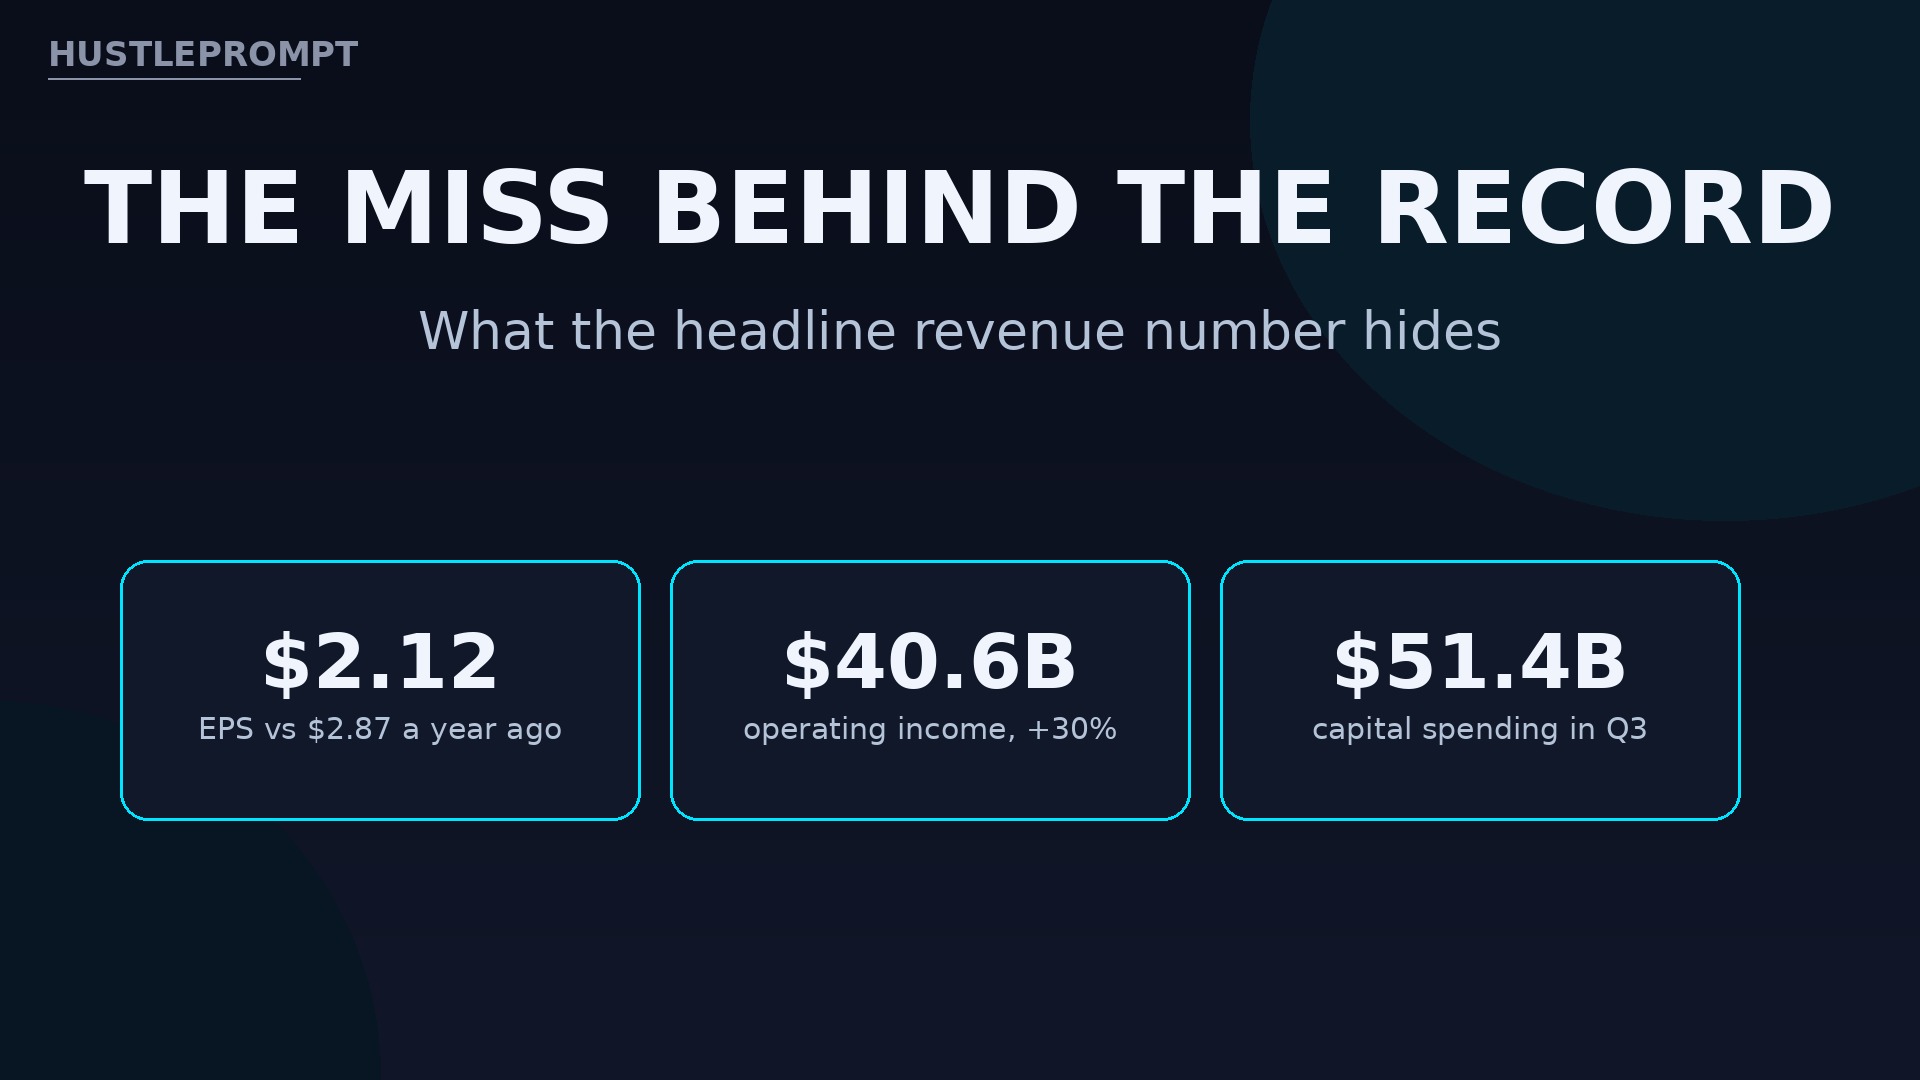
Strip out the market reaction and the quarter was enormous: operating income rose 30% to $40.6 billion, at a 31.8% margin.
Revenue: $127.577 billion, up 25% from $102.346 billion a year earlier.
Google Cloud: $30.709 billion, up 103%; operating income $11.121 billion versus $3.594 billion.
Operating income: $40.576 billion, up 30%, at a 31.8% margin.
Net income: $26.170 billion, or $2.12 per share, down from $2.87, after an $8.664 billion equity-securities loss.
Free cash flow: negative $9.065 billion, the second straight negative quarter.
Sundar Pichai put it bluntly: “We had a strong quarter and are now on a half-trillion dollar revenue run rate.” That run rate is real. So is the cash burn.
Revenue by segment, from the official release
| Segment | Q3 2026 revenue | Change |
|---|---|---|
| Google Search & other | $63.350 billion | +12% |
| YouTube ads | $11.207 billion | +9% |
| Subscriptions, platforms, devices | $14.290 billion | +11% |
| Google Cloud | $30.709 billion | +103% |
Search query growth hit its highest rate in five years, per the release, which credits AI features. Cloud’s story is sharper: revenue more than doubled on AI infrastructure and AI solutions demand, plus strong demand for TPU systems.
Why the stock fell anyway
Three things turned a record quarter into a selloff.
- The EPS miss was huge. Earnings of $2.12 per share came in well below the consensus of about $3.02 reported by market coverage, and below $2.87 a year earlier.
- A paper loss did most of the damage. Other income swung to an $8.221 billion expense from $12.759 billion of income a year earlier, driven by the $8.664 billion equity loss, which cut EPS by $0.55.
- Revenue narrowly missed too. The $127.577 billion total came in just under the roughly $128.22 billion consensus reported by market coverage.
The reaction was fast. Shares had closed up 1.6% at $324.89, then fell about 8% after hours, dipping below $300, per CNBC market data as reported. The paper loss explains the EPS miss, not the size of the drop.
The AI spending engine
Follow the cash: Alphabet is funding the largest infrastructure build in its history, and the bill now exceeds what the business throws off.
1. Cloud demand explodes. Google Cloud revenue jumps 103% to $30.7 billion.
2. Capex follows. Property and equipment purchases reach $51.355 billion in the quarter, per the release.
3. Cash flow goes negative: free cash flow of negative $9.065 billion, the second straight negative quarter.
4. The plan gets bigger, not smaller. Call coverage reports about $200 billion of capital spending for the full year, roughly $68 billion more in Q4, and about $924 billion in future purchase commitments.
Alphabet has gone three straight quarters without share repurchases for the first time since 2015, per FactSet data cited in coverage, while raising tens of billions in debt and stock to fund the buildout. The AI race is no longer paid for out of Search profits alone.
What the release says about AI
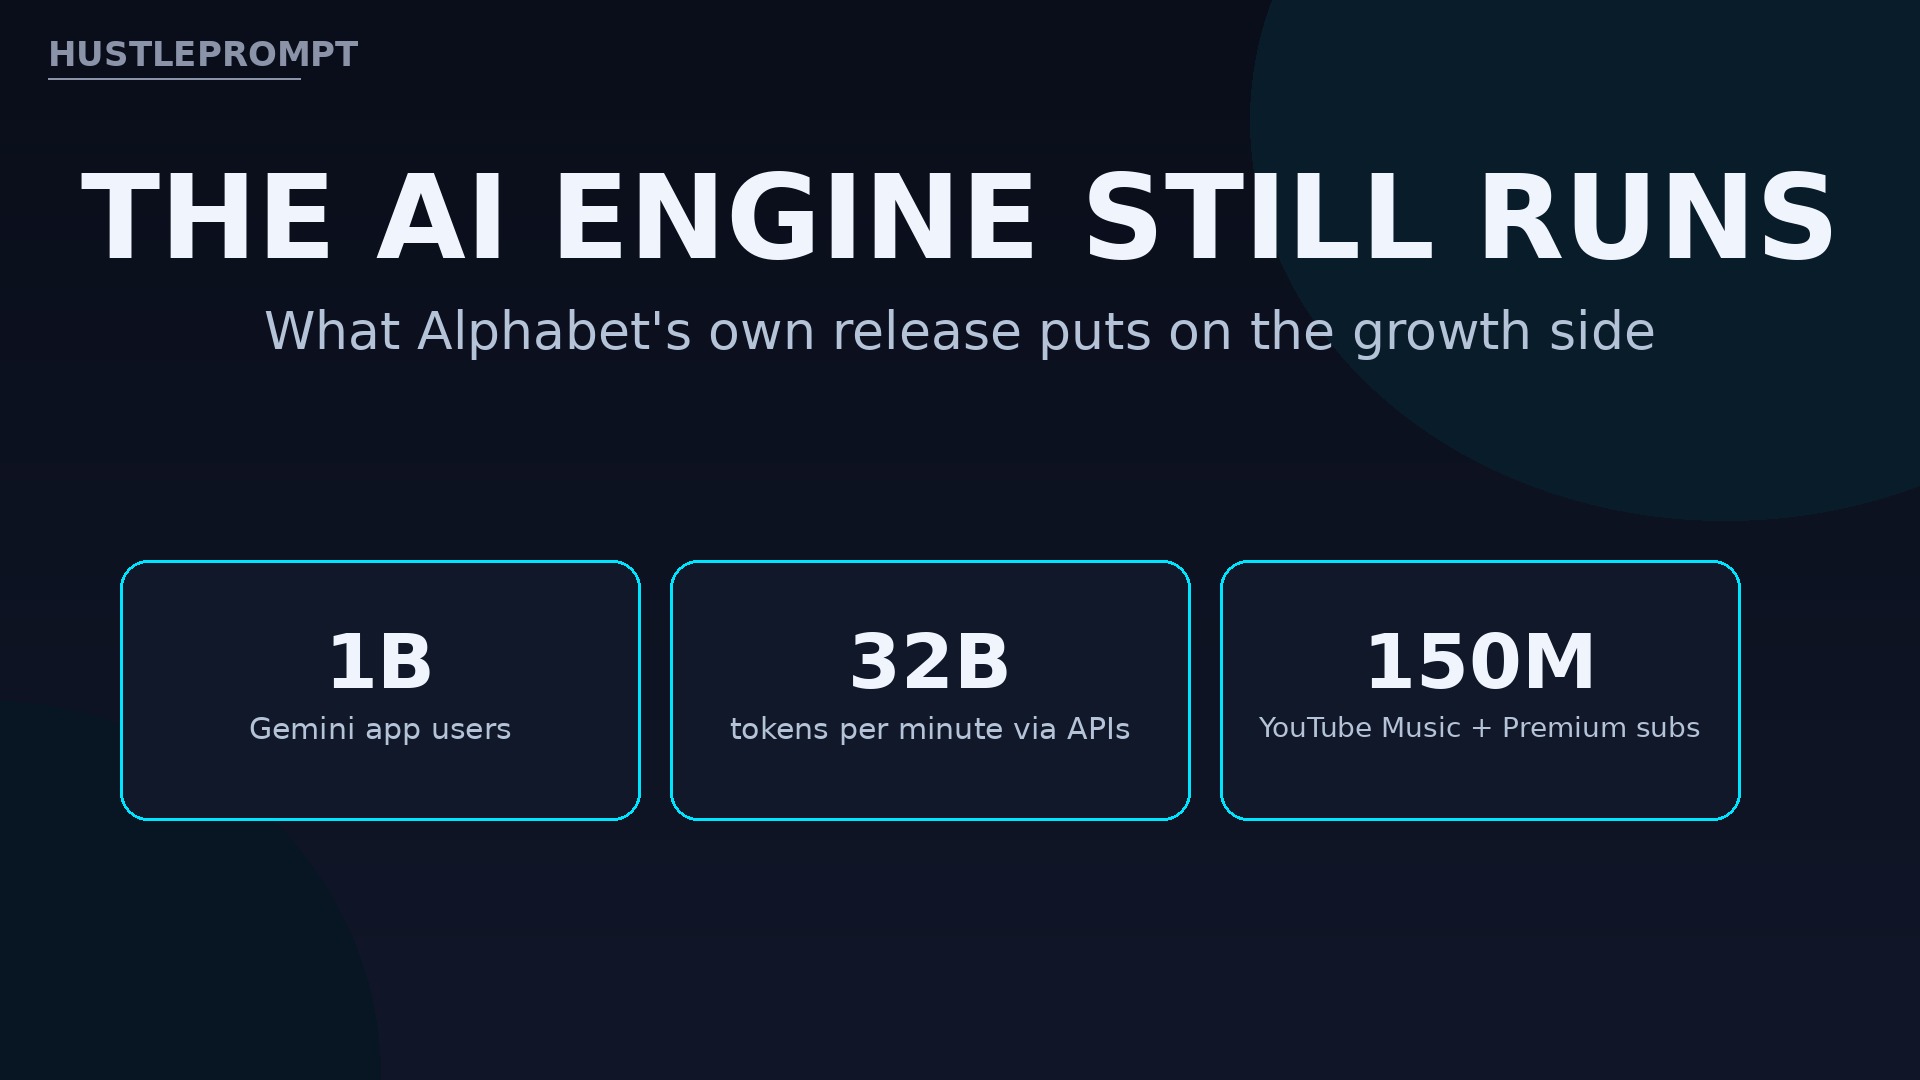
First-party model APIs now process nearly 32 billion tokens per minute, more than four times the volume of a year ago, and the release states Gemini 4 Argon and Carbon now lead at the frontier. The Gemini app has reached one billion users, and YouTube Music and Premium passed 150 million subscribers globally, including trials.
How to profit from Alphabet’s AI buildout
This is not investment advice, just a map of where the money in this release is flowing.
- Sell Google Cloud migration and AI services. Cloud grew 103% and its operating profit tripled; companies need help wiring AI features.
- Build on the Gemini API while volume quadruples. Nearly 32 billion tokens per minute means fast scaling, and products riding that API get cheaper distribution as the ecosystem grows.
- Offer TPU-adjacent consulting. The release cites strong TPU demand, and firms evaluating Google’s chips against Nvidia’s need independent guidance.
- Ride the subscription wave. YouTube Music and Premium passed 150 million subscribers, a growing paying audience for content and membership products.
- Watch the capex suppliers, not just the stock. A $200 billion buildout flows to data-center builders, chip suppliers, and power providers.
Frequently asked questions
Why did Alphabet stock fall if revenue grew 25%?
Because earnings missed badly: EPS of $2.12 versus about $3.02 expected, revenue narrowly below consensus, and free cash flow of negative $9.065 billion on $51.355 billion of capital spending.
What caused the EPS miss?
Mostly a paper loss: an $8.664 billion equity-securities loss, versus a $10.734 billion gain a year earlier, cutting net income by $6.7 billion and EPS by $0.55, per the official release.
What does negative free cash flow mean?
Alphabet spent more on capital projects than its operations generated in cash during the quarter. Q3 marked the second straight negative quarter.
How fast is Google Cloud growing?
Google Cloud revenue rose 103% to $30.709 billion, with operating income of $11.121 billion versus $3.594 billion a year earlier.
What did Sundar Pichai say about Gemini?
The release quotes Pichai on a half-trillion dollar revenue run rate, and states the Gemini app has reached one billion users, with first-party APIs processing nearly 32 billion tokens per minute.